• Home
  • Categories
    • real estate
    • technology
    • innovation
    • trends
    • insights
    • agents
    • investors
    • leadership
    • market analysis
    • future
March 27.2026
2 Minutes Read

Escalating Mortgage Rates Near 7%: The Impact of the Iran War

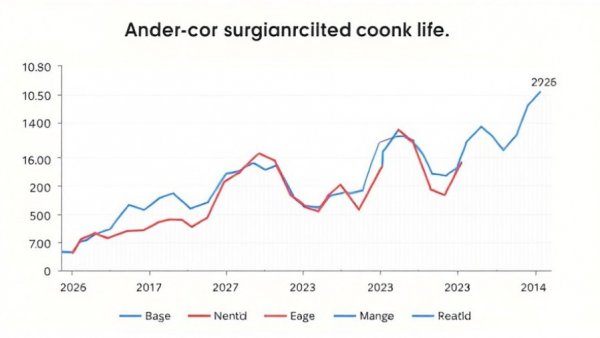
Line graph showing mortgage rates index trends for 2025 and 2026, Iran war impact analysis.

Mortgage Rates Surge Amid Global Unrest

The escalating war in Iran has quickly impacted financial markets, particularly in the real estate sector, causing average mortgage rates in the U.S. to drift alarmingly closer to the 7% mark. As the geopolitical climate heats up, the ripple effects are being felt far and wide, complicating the already delicate balance of home affordability in the nation. Currently, the 30-year fixed mortgage rate is hovering around 6.43%, significantly influenced by energy prices, which have surged due to the unrest in the Middle East.

Understanding the Connection between Oil Prices and Mortgage Rates

Mortgage rates are intricately linked to the yield on the 10-year U.S. Treasury note, which has seen increases alongside oil prices amidst the conflict in Iran. As reported, the yield on Treasury notes has risen to approximately 4.39%, from about 3.96% before the start of hostilities. With higher energy costs translating into inflationary pressures, the expectation of interest rate cuts appears less attainable, effectively locking in higher borrowing costs for homebuyers and renters alike.

Impacts on the Housing Market

The fear associated with rising mortgage rates is having a pronounced effect on the housing market. Applications for mortgages decreased by 10.5% this past week alone, amplifying concerns regarding homeownership aspirations, especially among younger consumers and first-time buyers. This trend illustrates a broader struggle within the market, which was already contending with supply limitations and job market uncertainties. As highlighted by experts from the Mortgage Bankers Association, escalating borrowing costs could keep prospective homebuyers sidelined, further exacerbating the inventory challenges facing the sector.

Potential Long-term Implications for Prospective Buyers

With mortgage rates likely to remain elevated due to geopolitical tensions, potential homebuyers may face daunting challenges in securing affordable housing. The expectation of economic headwinds, coupled with the continuing threat of inflation spurred by energy costs, could lead to a downturn in both home purchases and refinancing activities. The current economic landscape may force many to reconsider their financial priorities amid fluctuating market conditions, prompting a larger examination of affordability within the housing market.

Advice for Homebuyers Navigating a Volatile Market

For those contemplating purchasing a home in this uncertain financial climate, it's crucial to explore all available options thoroughly. Potential homebuyers should remain informed of market trends and consider fixed-rate mortgages over adjustable-rate loans to harness the predictability of stable payments in an unpredictable environment. Furthermore, tapping into various refinancing strategies can also help to mitigate costs given the current conditions. Homebuyers might greatly benefit from consulting financial professionals to evaluate their individual situations and devise effective plans moving forward.

A Call for Strategic Adaptation in Home Financing

As mortgage rates inch closer to 7%, the broader financial implications of the ongoing conflict in Iran cannot be overstated. The landscape of homeownership is changing, and both consumers and investors should prioritize adopting a proactive mindset in their financial planning.
market analysis

33 Views

0 Comments

Write A Comment

*
*
Please complete the captcha to submit your comment.
Related Posts All Posts
11.09.2026

How Lower Mortgage Rates Could Unlock Significant Housing Demand

Update Unleashing Pent-Up Demand: The State of the U.S. Housing Market The U.S. housing market is currently experiencing a significant bottleneck, as evidenced by the National Association of Realtors (NAR) chief economist Lawrence Yun, who has pointed out that there exists pent-up demand waiting to be unleashed. Yun highlighted that easing mortgage rates, improved inventory, and a rebound in consumer confidence could significantly alter this landscape. In 2000, existing-home sales peaked near 5.2 million, a stark contrast to the current projection of around 4 million for this year, even as the U.S. population has grown from 281 million to 350 million. The Role of Interest Rates and Consumer Confidence Interest rate fluctuations are a pivotal factor impacting the housing market. As mortgage rates remain elevated, potential buyers are left on the sidelines. Yun argued that should rates decline, an influx of buyers could enter the market, driven by rising incomes and a growing desire for homeownership. Consumer sentiment, however, plays an important role in this equation. Currently, confidence levels are about half of what they were in 2000, making buyers hesitant despite a labor market that continues to add jobs. The challenge now lies in boosting consumer sentiment, which has dipped significantly, matching levels seen during the Great Recession. Navigating the Challenges of First-Time Buyers First-time homebuyers are currently in a precarious position. NAR’s recent report indicates that they constituted only 22% of all buyers, a substantial drop from previous years, with the median age hitting 40. Factors such as rising rent, student loan debt, and childcare costs are all contributing to this demographic’s struggles in accessing homeownership. For lenders and real estate agents, this situation calls for a sharper focus on inventory, particularly affordable housing options, that can cater to this essential market segment. Seller Behavior and Market Dynamics Interestingly, sellers are holding onto their homes longer than ever, with the median duration reaching an all-time high of 12 years before selling. The phenomenon dubbed the "golden handcuffs" refers to homeowners reluctant to sell due to the low-interest mortgages they currently enjoy. This behavior significantly constrains the housing inventory, thereby exacerbating the challenges faced by first-time buyers. Lautz emphasizes the need for increasing affordable housing stock to relieve some of the pressure. Agent Usage and Transaction Trends Despite the rise in digital platforms, a remarkable 90% of buyers are still opting to purchase homes through licensed professionals, marking the highest level of agent utilization in four decades. This trend underscores the significance of expertise in real estate transactions. Agents are crucial not only for navigating the complexities of pricing and marketing homes but also for facilitating smooth transactions under the current market conditions. As the housing market braces itself for potential changes, the intersection of mortgage rates, consumer confidence, and inventory levels will dictate the trajectory moving forward. For real estate agents and investors alike, understanding these dynamics is vital for strategizing in an evolving landscape.

11.08.2026

Mortgage Rates Fall: What Buyers Need to Know About Inventory Trends

Update Mortgage Rates Are Falling: What This Means for BuyersRecent trends show a notable decrease in mortgage rates and a stabilization in demand, which may signal a shift in the housing market. Over the past three weeks, mortgage rates have consistently eased, which, coupled with a drop in inventory to 902,740 homes, merits a closer examination of how these factors are reshaping the landscape for prospective homebuyers. The Impact of the 10-Year Yield on Mortgage RatesThe relationship between the 10-year yield and mortgage rates has been under scrutiny lately. As highlighted in the 2026 HousingWire forecast, we anticipate mortgage rates fluctuating between 5.75% to 6.75%, contingent on the stability of the 10-year yield. Currently, the yield mechanisms appear to be holding firm at a key level of 5.35%. Any downward movement will be critical in determining whether mortgage rates can dip below the crucial threshold of 7%. Mortgage Spreads’ Influence: A Double-Edged SwordInterestingly, while mortgage spreads have seen a minor deterioration, they remain near multiyear lows. These trends indicate that while rates are stabilizing, any potential growth in demand will depend heavily on whether spreads can return to optimal levels. If they do revert to their stellar performance earlier this year, we could witness mortgage rates sinking below 7.25%, further stimulating demand. Pending Home Sales: A Reflection of Market HealthThe recent pending home sales data underscores the tenuous position of the current real estate market. While we are seeing a week-to-week stabilization in sales due to lower rates, it is essential to acknowledge that this shift does not signify a substantial growth trajectory. The data suggests that the threshold of 6.64% has historically been a tipping point for demand, with limited growth above 7%. How the Political Landscape Influences Mortgage RatesPolitical variables also loom large in this equation. In light of the recent midterm elections, any legislative changes could impact policies related to housing finance, potentially introducing measures that could either alleviate or exacerbate current mortgage conditions. What Congress decides will undoubtedly reverberate throughout the housing market.As we move deeper into the year, buyers and industry stakeholders should remain vigilant to market trends. Staying informed about mortgage rates and inventory levels will be crucial for effective decision-making in an evolving landscape.

11.07.2026

Jobs Report Surprises: Why Mortgage Rates Remain Stable Despite Solid Growth

Update Understanding the Unseen Catalysts of the Housing Market The recent October jobs report revealed a surprising stability in the mortgage market, even with robust payroll growth of 165,000 and a 4.1% unemployment rate. One might expect that such positive labor data would push mortgage rates upwards, particularly in our hawkish economic climate, but instead, rates remained relatively flat at 7.17%. This phenomenon prompts a deeper exploration into the dynamics at play in today’s financial environment. Analyzing the Subtle Influence of AI on the Market The primary driver behind mortgage rates this week appears not to be labor market conditions, but rather the performance of AI-related stocks. For instance, CoreWeave, a key player in AI infrastructure, saw its stock surge by 10% pre-market, which coincided with fluctuations in bond yields. Such market reactions indicate that investor sentiment around technology may be overshadowing traditional economic indicators like employment data. Labor Market Resilience Amidst Changing Circumstances The labor market has shown remarkable resilience since the disruptions caused by the COVID-19 pandemic. The significant drop in unemployment from 4.5% a year prior to 4.1% reflects improved labor conditions, but it also showcases a more nuanced landscape. Employers have adjusted strategies, with some relying on temporary labor reductions rather than full layoffs—a trend that safeguards overall employment levels despite economic uncertainty. The Role of Bond Market Trends in Real Estate Funding Despite strong job creation numbers, mortgage rates did not rise significantly, partly due to a muted reaction from bond markets. Investors are increasingly cautious, navigating the dual pressures of rising inflation and the upcoming political tensions that could reshape fiscal policy. Congress’s potential moves to manage AI development may profoundly impact funding sources for real estate, as they could introduce shifting financial paradigms in an already competitive market. Challenges for Construction: A Future Outlook One of the notable indicators of economic health is residential construction employment, which has not shown the typical downtrend observed in past cycles. While job growth in sectors like manufacturing and logistics emerges, construction employment appears stagnant at best. This situation poses risks if mortgage rates remain high or if AI expansions fail to sustain momentum. The complex interplay between these sectors will be critical for predicting future employment trends in real estate. Implications for Investors and Stakeholders For investors and stakeholders in the real estate market, understanding these dynamics is crucial. The current environment offers opportunities to leverage low mortgage rates while also grappling with potential fluctuations driven by stock market volatility and technological advances. Engaging with market trends and anticipating shifts in policy will equip stakeholders to navigate uncertainties effectively. Conclusion: Preparing for a Transformational Future As the economic landscape evolves, the interplay between job growth, technological advancements, and monetary policy will be essential. The recent jobs report, while positive, merely scratches the surface of a much more complicated economic reality. Investors should remain vigilant and adaptable, ready to capitalize on emerging trends while also preparing for potential downturns in sectors that currently show promise.

Resdefy TV

ResDefy TV is your go-to media channel for real estate innovation, marketing strategies, and community impact. We spotlight bold agents, smart tech, and breakthrough methods that drive real income, visibility, and goodwill.

COMPANY

  • Privacy Policy
  • Terms of Use
  • Advertise
  • Contact Us
  • Menu 5
  • Menu 6

4079524625

AVAILABLE FROM 8AM - 5PM

City, State

, ,

ABOUT US

From expert-led webinars to local press campaigns, ResDefy TV helps real estate pros grow their brand, generate leads, and lead with purpose.

© 2026 CompanyName All Rights Reserved. Address . Contact Us . Terms of Service . Privacy Policy

Terms of Service

Privacy Policy

Core Modal Title

Sorry, no results found

You Might Find These Articles Interesting

T
Please Check Your Email
We Will Be Following Up Shortly
*
*
*